Write your debt validation letter and count the days
A debt collector contacted you, and you want proof or disagree with the amount. Send a debt validation letter before the end date on your notice, about 30 days after it reaches you. Fill in your letter below and see how many days you have left.
Talk through this letter
You are disputing a debt in your state and want proof before you pay anything. Your written dispute pauses collection only if it is sent before the end date printed on the notice. Call our debt help line to talk through this letter and decide if a consumer lawyer should hear about it.
Talk to a consumer lawyer about this debt
Call (844) 393-5856- You call during business hours and say which debt it is.
- You answer a few questions about the debt and any court date.
- You decide whether a consumer lawyer sees your details.
Calls go to our debt help line during business hours. The call costs you nothing, and you give up nothing by calling. Debt Collector Lookup matches people with consumer lawyers; we are not a law firm or a debt collector.
Why does the letter make them pause?
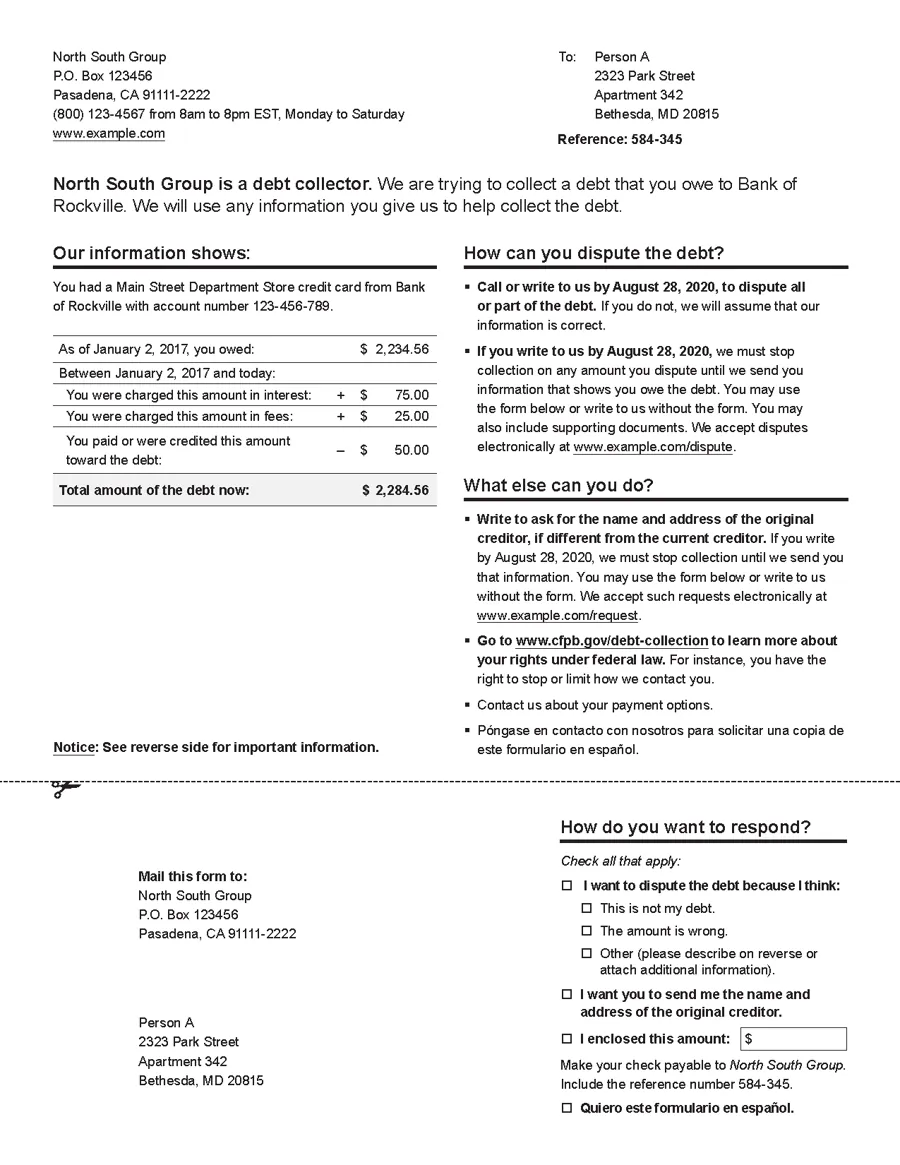
The collector's notice must name the creditor, the account and the amount. If you dispute in writing during the window, the collector must pause collecting the part you dispute until it sends proof.
30 days
Your window to dispute.
So your deadline is 30 days after you get the notice, or are assumed to get it.
Mail your letter before the end date printed on your notice.
five days
When the notice counts as received.
So the collector can treat the notice as received at least five days after sending, not counting weekends or holidays.
Check the end date printed on the notice instead of counting from the day it was sent.
September 1, 2026
New York City rule starts.
So New York City residents can dispute a debt at any point in the collection process.
Send your dispute in writing anyway, so you keep proof of it.
The 30 days and the five days are set by CFPB Regulation F.
How long do I have to dispute?
The notice comes with the first contact or within five days after it. It prints an end date for your dispute. Mail your letter before that date, and keep the certified mail receipt.
How do I send it?
Print the letter, sign it, and add the collector's mailing address from your notice. Send it by certified mail so you have proof of delivery. Keep a copy.
- Example: Odell got Midland's notice dated October 1. The end date on it is in early November, so he mails his letter the same week.
- Example: Winnie got a call from Portfolio Recovery Associates but no letter. She waits five days for the notice, then fills in its date.
- Example: Pete has an older notice. He reads its end date instead of counting from the date at the top.
What happens after I mail it?
The collector either sends proof, such as a copy of the bill, or stops. If the proof is right and the debt is yours, look at settling for less. If court papers arrive, see what to do when sued.
What changed in New York City in 2026?
Starting September 1, 2026, the New York City SHIELD rule lets city residents dispute a debt at any point during collection. Read the official notice.
Sources
- CFPB: what the notice must show (consumerfinance.gov).
- CFPB Regulation F, section 1006.34 (consumerfinance.gov).
- CFPB: model validation notice (consumerfinance.gov).
- FTC: debt collection FAQs (consumer.ftc.gov).
- NYC Consumer and Worker Protection: the SHIELD rule (nyc.gov).
Last checked October 2026.
What to do now
If your end date is close, mail your letter today and keep proof of delivery. Is the amount wrong, or does the collector ignore your dispute in your state? Call our debt help line or send the form. Sending the form costs nothing and does not send your letter for you.
Sending this costs nothing and commits you to nothing. We keep your answers with the collector's name, and you decide whether a consumer lawyer sees them. Debt Collector Lookup is not a law firm or a debt collector. The form does not schedule a call; to talk, call our debt help line during business hours.